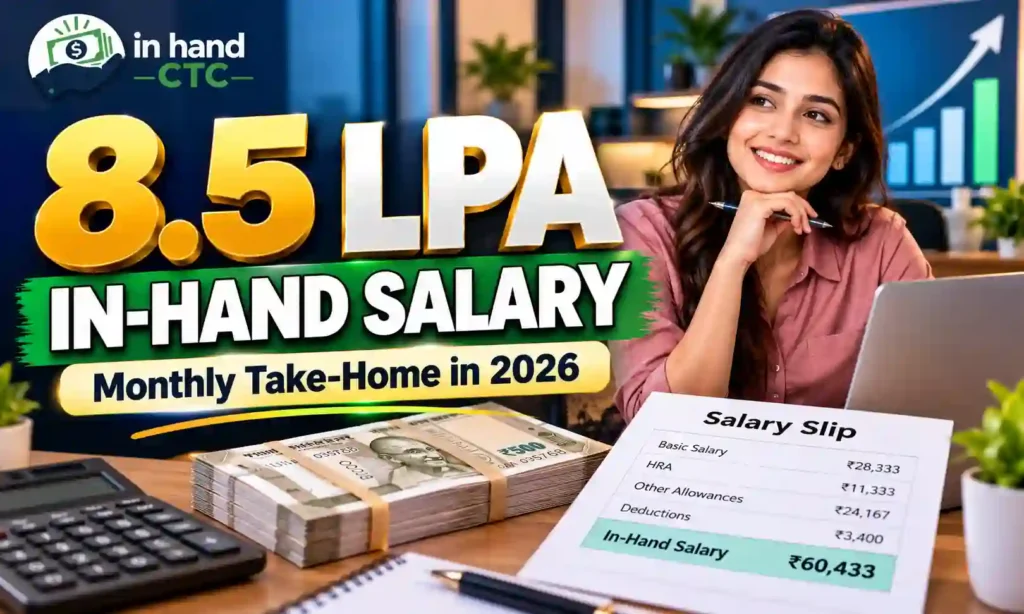
8.5 LPA in hand salary comes to about Rs. 62,471 per month in India for FY 2026-27 under a standard salary structure with PF calculated on the full basic. Depending on how your employer builds the package, the monthly credit can range from roughly Rs. 56,200 to Rs. 65,700. A yearly package of Rs. 8,50,000 looks like Rs. 70,833 a month on paper, yet that is not what lands in your account. Income tax does not touch a salary of this size under the new regime, so the difference comes from PF, gratuity and professional tax.
This guide shows the breakup line by line, explains the tax position, compares what you gain over a 8.5 LPA package, and helps you work out what rent, EMI and savings you can realistically plan around.
8.5 LPA Take Home Summary
| Scenario | Annual in hand | Monthly in hand |
|---|---|---|
| New regime, PF on full basic | Rs. 7,49,646 | Rs. 62,471 |
| New regime, PF capped at Rs. 1,800 per month | Rs. 7,88,046 | Rs. 65,671 |
| Old regime, rent Rs. 14,000 and Rs. 1.5 lakh in 80C | Rs. 7,49,646 | Rs. 62,471 |
| Old regime, no rent claim and only PF under 80C | Rs. 6,95,120 | Rs. 57,927 |
| New regime, 10% of CTC as variable pay | Rs. 7,59,441 | About Rs. 56,203 plus a yearly variable payout |
What the 8.5 LPA Figure Includes
An offer of 8.5 LPA is stated as Cost to Company. That total covers money paid to you every month and money the company sets aside on your behalf. Only the first part becomes salary.
| Term | Meaning |
|---|---|
| CTC | Total yearly cost of hiring you, including employer PF and gratuity |
| Gross salary | Basic, HRA and allowances paid as salary |
| In hand salary | Gross minus employee PF, professional tax and any income tax |
8.5 LPA CTC Breakup
A common structure keeps basic at 40% of CTC and HRA at 50% of basic, with the rest as special allowance. Employer PF is 12% of basic and gratuity is 4.81% of basic.
| Component | Annual (Rs.) | Monthly (Rs.) |
|---|---|---|
| Basic salary | 3,40,000 | 28,333 |
| HRA | 1,70,000 | 14,167 |
| Special allowance | 2,82,846 | 23,571 |
| Gross salary | 7,92,846 | 66,071 |
| Employer PF | 40,800 | 3,400 |
| Gratuity | 16,354 | 1,363 |
| Total CTC | 8,50,000 | 70,833 |
Your gross is about Rs. 4,760 a month lower than the headline monthly figure, before any deduction of your own.
Income Tax on 8.5 LPA
The new regime is the default for FY 2026-27, and the February 2026 Budget left the slabs unchanged. A standard deduction of Rs. 75,000 applies to salaried people, and a rebate makes taxable income up to Rs. 12 lakh effectively tax free.
| Step | Amount (Rs.) |
|---|---|
| Gross salary | 7,92,846 |
| Less: standard deduction | 75,000 |
| Taxable income | 7,17,846 |
| Tax on first Rs. 4,00,000 | 0 |
| Tax on remaining Rs. 3,17,846 at 5% | 15,892 |
| Tax before rebate | 15,892 |
| Less: rebate | 15,892 |
| Tax payable | Nil |
The slab tax of about Rs. 15,892 is fully cancelled by the rebate, so the income tax deducted from your pay should be zero. If your payslip shows monthly TDS at this package, ask HR to check which regime has been applied to you.
Your income tax-free runway is long. In this structure, tax only begins at a CTC of roughly Rs. 13.7 lakh, which leaves about Rs. 5.2 lakh of room above your current package.
8.5 LPA Monthly Salary Slip
| Earnings | Monthly (Rs.) |
|---|---|
| Basic salary | 28,333 |
| HRA | 14,167 |
| Special allowance | 23,571 |
| Gross salary | 66,071 |
| Deductions | Monthly (Rs.) |
|---|---|
| Employee PF | 3,400 |
| Professional tax | 200 |
| Income tax (TDS) | 0 |
| Total deductions | 3,600 |
Net in hand per month is about Rs. 62,471, which is Rs. 7,49,646 over a year, or about 88.2% of the CTC.
Moving From 7.5 LPA to 8.5 LPA: What the Extra Rs. 1 Lakh Gives You
If you are comparing a current job at 7.5 LPA with an offer of 8.5 LPA, here is the real difference under the same structure and regime.
| Item | 7.5 LPA | 8.5 LPA | Difference |
|---|---|---|---|
| Annual income tax | Nil | Nil | None |
| Annual in hand | Rs. 6,61,170 | Rs. 7,49,646 | Rs. 88,476 more |
| Monthly in hand | Rs. 55,098 | Rs. 62,471 | Rs. 7,373 more |
Because no tax applies to either package, you keep about 88% of the extra lakh. That works out to roughly Rs. 7,400 more every month, with the remainder going to additional PF and gratuity.
In Hand Salary With PF Capped at Rs. 15,000
PF is compulsory on a basic of up to Rs. 15,000 a month. Your basic here is above that, so a company that allows the ceiling would deduct only Rs. 1,800 from you and add Rs. 1,800 from its side.
| Component | Annual (Rs.) | Monthly (Rs.) |
|---|---|---|
| Gross salary | 8,12,046 | 67,671 |
| Employee PF | 21,600 | 1,800 |
| Professional tax | 2,400 | 200 |
| Income tax | 0 | 0 |
| Net in hand | 7,88,046 | 65,671 |
Take home rises by Rs. 3,200 a month. Since there is no tax, you keep every rupee of it. The trade-off is slower growth of your PF balance, so decide based on whether you prefer more cash now or a bigger retirement fund later.
Old Regime vs New Regime for 8.5 LPA
The old regime can match the new regime only when your deductions are large enough. Here are two situations.
| Item | Case A: rent claimed, 80C used | Case B: no rent, only PF in 80C |
|---|---|---|
| Gross salary | Rs. 7,92,846 | Rs. 7,92,846 |
| Standard deduction | Rs. 50,000 | Rs. 50,000 |
| HRA exemption (rent Rs. 14,000 a month) | Rs. 1,34,000 | Nil |
| Professional tax | Rs. 2,400 | Rs. 2,400 |
| Section 80C | Rs. 1,50,000 | Rs. 40,800 |
| Taxable income | Rs. 4,56,446 | Rs. 6,99,646 |
| Total tax with cess | Nil | Rs. 54,526 |
In Case A the taxable income falls below Rs. 5 lakh, so the old regime also gives zero tax. In Case B the old regime costs about Rs. 54,500 a year, while the new regime costs nothing. For most employees at this level, the new regime is the clear pick.
If Part of Your 8.5 LPA Is Variable
Suppose Rs. 85,000, or 10% of the CTC, is variable. Your fixed pay becomes Rs. 7,65,000, and basic, PF and gratuity are based on that smaller figure.
| Item | Amount |
|---|---|
| Fixed CTC | Rs. 7,65,000 |
| Variable pay | Rs. 85,000 per year |
| Monthly gross | About Rs. 59,463 |
| Monthly deductions (PF and professional tax) | About Rs. 3,260 |
| Monthly in hand | About Rs. 56,203 |
The variable part arrives once a year, linked to ratings or company results, and may come in below or above target. There is still no income tax due in the new regime.
City-Wise 8.5 LPA In Hand Salary
PF and tax rules are the same across India. Only professional tax, which each state decides, changes your take home by city.
| City | Professional tax | Monthly in hand (Rs.) |
|---|---|---|
| Delhi, Noida, Gurugram, Lucknow, Jaipur | Nil | 62,671 |
| Bengaluru, Hyderabad, Kolkata, Ahmedabad | Rs. 2,400 per year | 62,471 |
| Mumbai, Pune, Chennai | About Rs. 2,500 per year | 62,462 |
The numbers are very close. Rent and everyday costs create the real difference between cities.
8.5 LPA Compared With Nearby Packages
| CTC | Annual income tax | Monthly in hand (Rs.) |
|---|---|---|
| 7.5 LPA | Nil | 55,098 |
| 8 LPA | Nil | 58,784 |
| 8.5 LPA | Nil | 62,471 |
| 9 LPA | Nil | 66,157 |
| 10 LPA | Nil | 73,530 |
Each extra Rs. 50,000 of CTC in this range adds about Rs. 3,700 to your monthly in hand.
How Much Rent and EMI Can You Afford?
A simple rule many people follow is to keep rent between 25% and 35% of take home, and total EMIs within 40% to 50%.
| Item | Guideline | Monthly amount (Rs.) |
|---|---|---|
| Rent at 25% of take home | Comfortable | 15,618 |
| Rent at 30% of take home | Common ceiling | 18,741 |
| Rent at 35% of take home | Stretching the budget | 21,865 |
| Total EMI limit at 45% | Typical bank view | About 28,100 |
At an EMI of about Rs. 28,100 and an assumed 8.5% rate over 20 years, a home loan of roughly Rs. 32 lakh is possible. Your credit score, other loans and job stability will change the real figure.
Ways to Improve Your Take Home
- Ask about PF on the Rs. 15,000 ceiling. It can add about Rs. 3,200 a month, at the cost of a smaller PF balance.
- Skip tax-saving purchases made only for the tax benefit. With nil tax under the new regime, 80C or NPS products give no tax advantage. Choose investments for your goals.
- Check TDS on your payslip. Any income tax at this level is worth querying.
- File your return every year. It helps with loans and visas and lets you claim any excess TDS.
- Compare structures, not just totals. A package with a bigger fixed share can be better than a higher headline with uncertain bonuses.
Sample Monthly Budget on About Rs. 62,500
| Category | Share | Monthly (Rs.) |
|---|---|---|
| Needs: rent, food, bills, transport | 50% | 31,250 |
| Wants: shopping, outings, subscriptions | 30% | 18,750 |
| Savings and investments | 20% | 12,500 |
A good order for the savings part is an emergency fund first, then health and term insurance, then regular investing. In expensive cities, sharing accommodation is a common way to protect the savings share.
Gratuity on 8.5 LPA
Gratuity usually becomes payable after five years of continuous service and equals last drawn monthly basic times 15, divided by 26, times years of service. With a basic of about Rs. 28,333, five years gives roughly Rs. 81,731.
Is 8.5 LPA a Good Salary?
It depends on where you live and what you spend. For someone early in their career who shares a flat or lives with family, it allows steady saving and a comfortable routine. For someone paying full rent in a costly metro and supporting dependents, the budget is tighter. One clear advantage is that you keep nearly 88 paise of every rupee of CTC, since no income tax applies.
Questions to Ask Before Accepting an 8.5 LPA Offer
- Is the whole 8.5 LPA fixed, or does it include variable pay?
- Is PF on the full basic or on the Rs. 15,000 ceiling?
- Are insurance and gratuity inside the CTC?
- Is any joining bonus repayable if you leave early?
- What are the notice period, probation terms and appraisal cycle?
Conclusion
The 8.5 LPA in hand salary is about Rs. 62,471 a month under a standard structure. It rises to around Rs. 65,671 if PF is capped and falls to about Rs. 56,203 if a tenth of the CTC is variable. No income tax is due under the new regime, so the gap between your package and your paycheck comes from PF, gratuity and professional tax. Ask your employer for the full breakup and plan your spending around the real monthly credit.
All figures are estimates based on common salary structures and the tax rules for FY 2026-27. Your actual payslip may differ.
Frequently Asked Questions
What is the monthly in hand salary for 8.5 LPA?
For a standard structure with PF on the full basic, it is about Rs. 62,471 per month. If PF is limited to the Rs. 15,000 ceiling, it rises to roughly Rs. 65,671.
Is 8.5 LPA the CTC or the take home?
It is the CTC in almost every offer. The take home is lower after employer PF, gratuity, your own PF and professional tax.
Is income tax charged on an 8.5 LPA salary?
No. Under the new regime for FY 2026-27, the rebate makes income up to Rs. 12 lakh effectively tax free, and an 8.5 LPA package is well inside that limit.
Which tax regime is better for 8.5 LPA?
The new regime gives nil tax with no paperwork. The old regime can also give nil tax if you claim HRA and use 80C fully, but it costs about Rs. 54,500 if you claim neither.
How much PF is cut from an 8.5 LPA salary?
On a full basic of about Rs. 28,333, your share is Rs. 3,400 a month. On the Rs. 15,000 ceiling, it is Rs. 1,800 a month.
How much more do I get compared with 7.5 LPA?
About Rs. 7,373 more per month in hand, or roughly Rs. 88,476 more a year, under the same structure and regime.
Does my city change the 8.5 LPA in hand salary?
Only slightly, through professional tax. The difference is a few hundred rupees a year at most, while rent changes much more.
How much home loan can I get on 8.5 LPA?
With a take home near Rs. 62,471, a 45% EMI limit and an assumed 8.5% rate for 20 years, around Rs. 32 lakh is a fair estimate.
Why is my payslip different from this calculation?
Common reasons are variable pay not paid monthly, PF on full basic, insurance premiums deducted from pay and a different split between basic and allowances. Ask HR for the detailed salary breakup to find the gap.
Also know: 8 LPA In Hand Salary in 2026: Monthly Salary, PF, Tax and CTC Breakdown